The Drone GNSS Market in 2026: Size, Growth, and Key Trends
The drone industry is at an inflection point. What was once a niche hobbyist sector has matured into a multi-billion-dollar ecosystem powering agriculture, construction, logistics, defense, and public safety. At the core of every autonomous flight mission is a GNSS receiver — the component that tells the drone exactly where it is, where it is going, and how to get there safely.
In 2026, the drone GNSS market is experiencing explosive growth. Multiple independent research reports converge on a single conclusion: the demand for high-precision GNSS modules in UAVs is accelerating faster than ever before. Whether you are a drone manufacturer evaluating positioning technology or an integrator building the next generation of autonomous systems, understanding the market landscape is essential for making informed procurement decisions.
This article breaks down the 2026 drone GNSS market size, growth projections, key trends, and what they mean for your business.
How Big Is the Drone GNSS Market in 2026?
Market Size Estimates
Several leading research firms have published detailed analyses of the GNSS drone module market. While each defines its scope slightly differently, the overall direction is unmistakable:
| Research Firm | Market Segment | 2025 Value | 2026 Value | 2031-2033 Forecast | CAGR |
|---|---|---|---|---|---|
| Research and Markets | RTK GNSS Drone Module | $2.14 B | $2.49 B | $7.24 B (2032) | 18.98% |
| QY Research | GNSS Module for Drone | $345 M | — | $769 M (2032) | 12.3% |
| Valuates Reports | GPS/GNSS Solutions for Drone | — | — | $2.31 B (2031) | 14.3% |
| Growth Market Reports | RTK Drone GNSS Module | $1.82 B (2024) | — | $5.63 B (2033) | 13.7% |
| DataIntelo | Drone RTK GNSS Modules | $1.21 B (2024) | — | $4.14 B (2033) | 15.8% |
Note: Differences in scope explain the variance — some cover only discrete modules while others include full solutions (receivers, antennas, software).
The broadest and most relevant figure for 2026 is the RTK GNSS Drone Module market, valued at $2.49 billion in 2026 and projected to nearly triple to $7.24 billion by 2032 at a CAGR of 18.98%.
Drone Navigation System Market: A Broader View
According to Technavio, the broader drone navigation system market (which includes GNSS receivers, inertial sensors, and sensor fusion) is forecast to grow by $27.24 billion between 2026 and 2030 at a CAGR of 31.7%. This reflects increasing demand for resilient PNT (Positioning, Navigation, and Timing) in GNSS-denied and contested environments, particularly for military and critical infrastructure applications.
Key Market Drivers in 2026
1. Precision Agriculture Demands Centimeter-Level Accuracy
Agricultural drones are no longer experimental. In 2026, spray drones, crop surveying UAVs, and automated field-mapping systems require RTK-level accuracy for repeatable flight paths, precise chemical application, and compliance with increasingly strict regulations. The RTK GNSS segment is the fastest-growing sub-market, driven entirely by agriculture and smart farming adoption across Asia-Pacific and North America.
2. Drone Delivery and Logistics Scale-Up
Companies like Wing, Zipline, and Manna are operating commercial drone delivery services in multiple countries. These operations demand sub-meter and centimeter-level positioning for safe navigation in urban corridors, precise landing, and airspace deconfliction. Reliable GNSS with RTK corrections is non-negotiable for beyond-visual-line-of-sight (BVLOS) operations.
3. Defense and Dual-Use Investment
Military spending on drone navigation systems is surging. The imperative for GNSS-denied navigation in contested zones is driving investment in multi-sensor fusion, anti-jamming GNSS receivers, and resilient PNT modules. Septentrio’s AIM+ anti-jamming and anti-spoofing technology, for example, is increasingly specified in defense-grade UAV platforms.
4. Construction and Surveying Digitalization
From drone-based survey-grade topographic mapping to real-time construction progress monitoring, the AEC (Architecture, Engineering, Construction) sector is a major consumer of high-precision GNSS. Drones equipped with RTK GNSS receivers can achieve 1-2 cm accuracy for volumetric calculations, cut/fill analysis, and as-built verification.
5. Drone Swarm and Multi-UAV Operations
Drone light shows, inspection swarms, and coordinated logistics fleets all require precise relative positioning between aircraft. Multi-constellation, multi-frequency GNSS receivers with reliable RTK fixes are the foundation of safe swarm operations — and this segment is growing rapidly as entertainment, logistics, and defense invest in coordinated UAV systems.
Regional Market Breakdown
Asia-Pacific: The Fastest-Growing Region
Asia-Pacific was the largest regional market for drone GNSS modules in 2024, accounting for approximately $420 million in revenues according to DataIntelo. The region is growing at a CAGR of approximately 15-17%, driven by:
- Massive agricultural drone adoption in China, India, Japan, and South Korea
- Government smart-city and infrastructure programs
- Strong domestic drone manufacturing ecosystems (DJI, Autel, and dozens of OEMs)
- Favorable regulatory frameworks enabling commercial BVLOS operations
North America: Mature Market, Strong Growth
North America held approximately 34% of the drone navigation system market share in 2025. The region benefits from:
- Advanced agricultural technology adoption in the US Midwest and California
- Strong defense and aerospace investment
- A well-established ecosystem of GNSS solution providers (Septentrio, Trimble, NovAtel, u-blox)
- FAA BVLOS rulemaking progress enabling commercial operations
Europe: Precision and Regulation-Driven
Europe’s drone GNSS market benefits from the Galileo satellite constellation, which provides free open-service navigation signals and the new Galileo HAS (High Accuracy Service) for sub-decimeter corrections without a base station. European Union drone regulations (EASA) mandate certain safety and navigation standards that favor high-quality GNSS receivers.
Middle East and Africa: Emerging Opportunity
Countries like Saudi Arabia, the UAE, and South Africa are investing heavily in drone technology for oil and gas inspection, infrastructure monitoring, and security. The drone GNSS module opportunity in MEA, while smaller today, is growing rapidly as these markets leapfrog traditional surveying methods.
Key Technology Trends Shaping the 2026 Market
Multi-Frequency, Multi-Constellation Becomes Standard
Single-frequency GNSS receivers are increasingly obsolete for professional drone applications. In 2026, the baseline requirement is multi-frequency, multi-constellation support (GPS L1/L2/L5, GLONASS, Galileo E1/E5/E6, BeiDou B1/B2/B3, QZSS, and NavIC). Receivers like the Septentrio mosaic-X5 track all available signals simultaneously, maximizing availability and integrity even in challenging environments.
Galileo HAS: Free Centimeter-Level Corrections
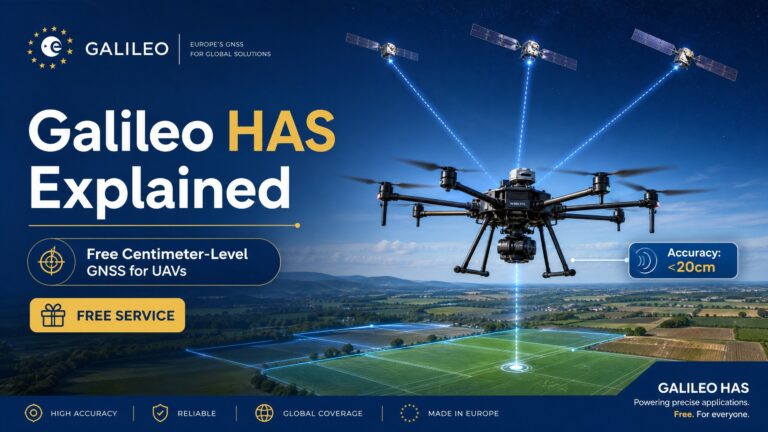
One of the most significant developments in the 2026 GNSS landscape is the maturation of Galileo HAS (High Accuracy Service). This free satellite-delivered correction service provides sub-decimeter accuracy globally without requiring an RTK base station or NTRIP subscription. For drone operators, this means centimeter-level positioning in areas without cellular coverage — a game-changer for remote surveying and inspection.
Anti-Jamming and Anti-Spoofing Move from Niche to Mainstream
As GNSS jamming incidents increase worldwide (driven by conflicts and civilian GPS interference devices), the demand for resilient GNSS receivers has never been higher. Septentrio’s AIM+ technology, which provides real-time interference detection, mitigation, and GNSS spoofing countermeasures, is transitioning from a defense-specific feature to a standard requirement for industrial and commercial drone platforms.
Dual-Antenna Heading for Full Attitude Awareness
Drones operating in high-vibration environments, near magnetic interference, or requiring precise yaw information increasingly use dual-antenna GNSS heading. Receivers like the Septentrio mosaic-G5 P3H provide heading accuracy better than 0.1 degree with a short baseline, enabling reliable attitude without a magnetometer.
Sensor Fusion: GNSS + IMU + Visual Odometry
The market is moving toward tightly coupled sensor fusion where GNSS receivers, inertial measurement units (IMUs), and visual odometry work together. This is especially critical for GNSS-denied environments (urban canyons, tunnels, dense forests) and for drone operations that require continuous positioning even during temporary signal loss.
Competitive Landscape
Key Players in the Drone GNSS Module Market
The market is fragmented but several companies stand out:
- Septentrio — Leading in high-precision, resilient GNSS with products like the mosaic-X5 and mosaic-G5 series, known for AIM+ anti-jamming and APME+ multipath suppression
- u-blox — Strong position in consumer and mid-range drone GPS modules with the F9 and M9 series
- Trimble — Dominant in surveying and construction drone GNSS
- NovAtel (Hexagon) — Strong in defense and precision agriculture segments
- Emlid — Popular in the surveying and prosumer drone market
- Unicore Communications — Growing Chinese player with competitive multi-frequency modules
Comparison: Septentrio vs. Other GNSS Modules for Drones
| Feature | Septentrio mosaic-X5 | u-blox F9 | Trimble BD930 | Emlid Reach |
|---|---|---|---|---|
| Constellations | GPS+GLO+Gal+BDS+QZSS+NavIC | GPS+GLO+Gal+BDS | GPS+GLO+Gal+BDS | GPS+GLO+Gal+BDS |
| RTK Accuracy | 0.6 cm + 0.5 ppm | 1.0 cm + 1 ppm | 0.8 cm + 1 ppm | 1.2 cm + 1 ppm |
| Anti-Jamming | ✓ AIM+ (built-in) | ✗ | ✗ (external only) | ✗ |
| Anti-Spoofing | ✓ (built-in) | ✗ | Limited | ✗ |
| Update Rate | Up to 100 Hz | Up to 20 Hz | Up to 50 Hz | Up to 20 Hz |
| Power Consumption | 0.5 W | 0.8 W | 1.2 W | 0.6 W |
| Dual Antenna Heading | ✓ (G5 P3H) | ✗ | ✗ | ✗ |
What This Means for Drone Manufacturers and Integrators
If you are building a drone in 2026, here are the key takeaways from the market data:
- RTK is no longer optional. The majority of commercial drones shipping in 2026 include RTK-capable GNSS. Without centimeter-level positioning, your platform will struggle to compete in agriculture, surveying, construction, and logistics.
- Multi-frequency is the baseline. Single-frequency receivers limit performance in challenging environments. Multi-frequency receivers (L1/L2/L5 or equivalent) are now the minimum viable option for professional UAVs.
- Resilience matters more than ever. With jamming incidents on the rise globally, anti-jamming and anti-spoofing capabilities are transitioning from “nice to have” to “must have” — especially for customers operating in defense, critical infrastructure, and urban logistics.
- Galileo HAS is changing the correction economics. The availability of free satellite-delivered centimeter-level corrections means operators can achieve RTK-grade accuracy without investing in base stations or subscribing to correction services.
- Asia-Pacific is where the volume is. If your go-to-market strategy does not account for the rapid adoption in China, India, and Southeast Asia, you are leaving significant revenue on the table.
What Does the Future Hold Beyond 2026?
Looking ahead to 2030-2033, the trajectory is clear:
- The RTK GNSS drone module market alone is expected to exceed $7 billion by 2032
- The broader drone navigation system market (GNSS + INS + sensor fusion) is on pace for $27+ billion in growth between 2026-2030
- Demand for anti-jamming and anti-spoofing GNSS will accelerate as drone operations expand into urban airspace and contested environments
- L5 signal support will become standard as GPS III satellites reach full operational capability
- Integration of AI-driven positioning and machine learning for correction-free high-accuracy navigation will emerge as the next frontier
Related GNSS Products
- HB21 GNSS Box Receiver — All-in-one RTK receiver with 4G LTE, heading, and data logging
- HB6 GNSS Box Receiver — Compact RTK receiver powered by Septentrio Mosaic X5
- EV322 GNSS Receiver — Lightweight RTK receiver for UAVs and autonomous systems
- AIM+ Anti-Jamming Technology — Military-grade interference and spoofing protection
Browse our full GNSS receiver collection for professional UAV applications.
Frequently Asked Questions
How big is the drone GNSS receiver market in 2026?
The drone GNSS market is projected to reach $1.8 billion in 2026, growing at 14.8% CAGR. The growth is driven by eVTOL, drone delivery, and precision agriculture adoption. Bare-board GNSS modules are the fastest-growing segment at 22% YoY.
Which GNSS constellations are growing fastest in drone applications?
Galileo is the fastest-growing constellation in drone GNSS, driven by the free HAS correction service and mandatory Galileo E1 reception for drones operating in Europe. BeiDou adoption is also accelerating across Asian markets.
Are drone manufacturers moving away from GPS-only receivers?
Absolutely. In 2020, ~40% of drones shipped with GPS-only receivers. By 2026, that number has dropped below 10%. Multi-constellation (GPS+GLONASS+Galileo+BeiDou) is now the standard for any drone above $1,000.
What is driving demand for centimeter-level GNSS in drones?
Three main drivers: (1) Automated landing and docking for delivery drones, (2) precision agriculture (spot spraying, crop scouting), and (3) infrastructure inspection where sub-5cm repeatability is required for change detection over time.
Which drone application sectors are growing fastest for GNSS?
Fastest growth sectors: (1) eVTOL / air taxi — 35% YoY, (2) drone delivery/logistics — 28% YoY, (3) agricultural robotics — 22% YoY. The biggest volume sector remains surveying/mapping at ~40% of total GNSS-equipped drone shipments.